
Personal Financial Planner & Adviser
Financial Advice for All Your Important Life Decisions
I’m James Hayes, an AFP® independent financial adviser based in Caringbah. For 15+ years, I’ve been helping pre-retirees, retirees, HNWIs, and real estate investors across the Sutherland Shire, Inner West, and Greater Sydney make sense of super, TTR, investments, insurance, pension, wills & estate planning. Bring me the questions that keep you up at night.
- Licensed
- Unaffiliated
- Worth It
Work With Me
Who Are My Ideal Clients?
The people I work best with fall into these two groups:
Pre-retirees & Retirees (55–65)
You’ve worked hard, raised a family, and now you’re ready to think about easing out of work. You may be wondering: Will my super be enough? How do I set up an income stream? Can I retire sooner than I think?
Wealth Builders (35–50)
You’re in the thick of your career, earning well, and thinking about the long game. Maybe you want help setting up a self-managed super fund, investing in shares and ETFs, or buying your first or next investment property.
If either sounds like you, let’s talk. If you’re after Centrelink Jobseeker support, debt consolidation, or ways to withdraw super early, I’m not the right fit, and I’d rather be upfront about that.
What I Do
Financial Planning Services
Money means different things at different stages of life. These are the areas where I can step in and help take the pressure off:
Superannuation
Make the most of your super or SMSF, from regular contributions through to withdrawals and tax-free pensions, so you feel confident at every stage of life.
Learn more about SuperannuationTransition to Retirement
Structure your income streams as you ease out of work, while keeping your lifestyle and tax planning on track.
Learn more about Transition to RetirementRetirement
Put together a forward-thinking income strategy to make sure your money outlasts you rather than the other way around.
Learn more about RetirementInheritance
Manage your family inheritances in a tax-smart way, so that wealth is preserved and distributed as smoothly as possible.
Learn more about InheritanceInsurance
Review your life, TPD, and income protection cover to check it matches what you'd need, not what a default setting in your super fund gave you.
Learn more about InsuranceShares & ETFs
Build and manage portfolios of shares and ETFs, with strategies designed to balance growth potential against sensible risk.
Learn more about Shares & ETFsProperty Investment
Receive guidance on when and how property can play a role in your broader financial plan, including super and tax considerations.
Learn more about Property InvestmentAge Pension
Set up reliable tax-free retirement income streams that give you security today while protecting your financial future.
Learn more about Age PensionAged Care Planning
Support yourself or a loved one through aged care decisions, from costs and entitlements to long-term sustainability.
Learn more about Aged Care PlanningFirst Home Buying
Step into the property market with trustworthy, age-appropriate strategies for saving, borrowing, and long-term planning.
Learn more about First Home BuyingEthical Investing
Design investment strategies that line up with your personal values while being conducive to long-term growth.
Learn more about Ethical InvestingWills & Estate Planning
Ensure that your assets are protected, your wishes are carried out, and your loved ones are supported into the future.
Learn more about Wills & Estate PlanningWealth Management
Sophisticated portfolio construction and tax-effective structuring for wealth builders and HNWIs looking to grow and protect their capital.
Learn more about Wealth Management
Personalised Plans | No External Influence | No Templates
Why Choose James Hayes
Get understandable, unbiased advice on perplexing financial scenarios. Here is why you might enjoy working together:
Completely and Fiercely Independent
I own my business. I don’t work for a bank or a corporate entity. That means no product quotas to hit and no boss telling me what to recommend. My advice is focused entirely on your goals, values, and the life you want to live.
Work With One Person Throughout
Big firms swap advisers around every few years. If you choose to work with me, you won’t have to re-explain your life to a new person every time you book an appointment. I’ll still be the one in your corner ten years from now.
Explanations in Simple English
Super rules and tax options are confusing and unexciting to non-financial people. With words and a whiteboard, you will see, and not just hear, where you are today and how you’ll get to where you want to be.
Easy to Reach, Quick to Respond
“Call the office and leave a message” isn’t how anyone wants to reach their adviser. You won’t have to leave messages with the front desk or wait days for a reply. Stay in touch with me through text, email, or in person.
Honest Answers from Day Zero
If I can help you, I’ll tell you how straight up without a sales pitch or the pressure of obligation. If I’m not the right person for what you need, I’ll tell you that too and point you toward someone who is.
What To Expect
Process
Step 1: Quick Call
We begin with an obligation- and cost-free 15-minute chat where you tell me a little about your situation and I explain how I work. It’s a chance for us to see if I’m the right fit, and I’ll be upfront if I don’t think I can add value to your situation.
Step 2: Planning Session
If it makes sense to go further, we sit down together. I’ll map out your options, run through the numbers, and show you what life could look like a year from now. Most people leave this session saying they finally feel like things make sense.
Step 3: Your Strategy
After that session, you walk away with a plan that’s realistic, implementable, and built around your goals. If you want ongoing support, I’ll stay by your side to update the plan as your life changes and new opportunities or challenges come up.
Testimonials
Client Experiences
A few words from people who’ve sat where you’re sitting now.
I was attracted to James’s business by the online referees and comments and have since been very happy with the choice. James has been very patient and professional in rebuilding my superannuation portfolio and the results are pleasing. I very much appreciate his depth of knowledge and his personal skills.
Geoffrey Todd
We have found dealing with James a worthwhile experience as he listens to what you require and that investments are reviewed and information to us is clear. We found James helped our transition into retirement an easy experience and very grateful for his expertise. 5 stars all the way !!
Craig Pullen
James was incredibly helpful and prompt in his responses. Very accurate in the analysis of the real estate market and my personal, financial circumstances. In just a few hours we understood the best-case scenario, in my situation, and he guided me towards positive and reassuring final decisions to be made. He really placed my personal and financial needs first and we went from there. I really appreciated the honesty in his judgment and of course his valuable knowledge.
Marta Lentisco
Locations
Suburbs
I’m based in Caringbah and opening a second practice in Inner West. Most of the people I work with live right here in the Shire or Inner West. If you’re nearby, chances are I already have clients in your suburb, which makes it easy to catch up in person when you need to.
Sutherland Shire
- Alfords Point
- Audley
- Bangor
- Barden Ridge
- Bonnet Bay
- Bundeena
- Burraneer
- Caringabah
- Caringbah South
- Caravan Head
- Como
- Como West
- Cronulla
- Dolans Bay
- Engadine
- Grays Point
- Greenhills Beach
- Gundamaian
- Gymea
- Gymea Bay
- Heathcote
- Illawong
- Jannali
- Kangaroo Point
- Kareela
- Kirrawee
- Kurnell
- Lilli Pilli
- Loftus
- Lucas Heights
- Maianbar
- Menai
- Miranda
- Oyster Bay
- Port Hacking
- Royal National Park
- Sandy Point
- Sutherland
- Sylvania Heights
- Sylvania Waters
- Taren Point
- Warumbul
- Waterfall
- Woolooware
- Woronora
- Woronora Dam
- Woronora Heights
- Yarrawarrah
- Yowie Bay
Inner West
- Alexandria
- Annandale
- Ashbury
- Ashfield
- Balmain
- Balmain East
- Birchgrove
- Camperdown
- Croydon
- Croydon Park
- Dulwich Hill
- Earlwood
- Enmore
- Erskineville
- Forest Lodge
- Glebe
- Haberfield
- Hurlstone Park
- Leichhardt
- Lewisham
- Lilyfield
- Marrickville
- Newtown
- Petersham
- Rozelle
- St Peters
- Stanmore
- Summer Hill
- Sydenham
- Tempe
If you don’t see your suburb listed, that doesn’t rule you out because I also work with clients across Sydney and the CBD who prefer an adviser close to home in the Shire or Inner West.
About
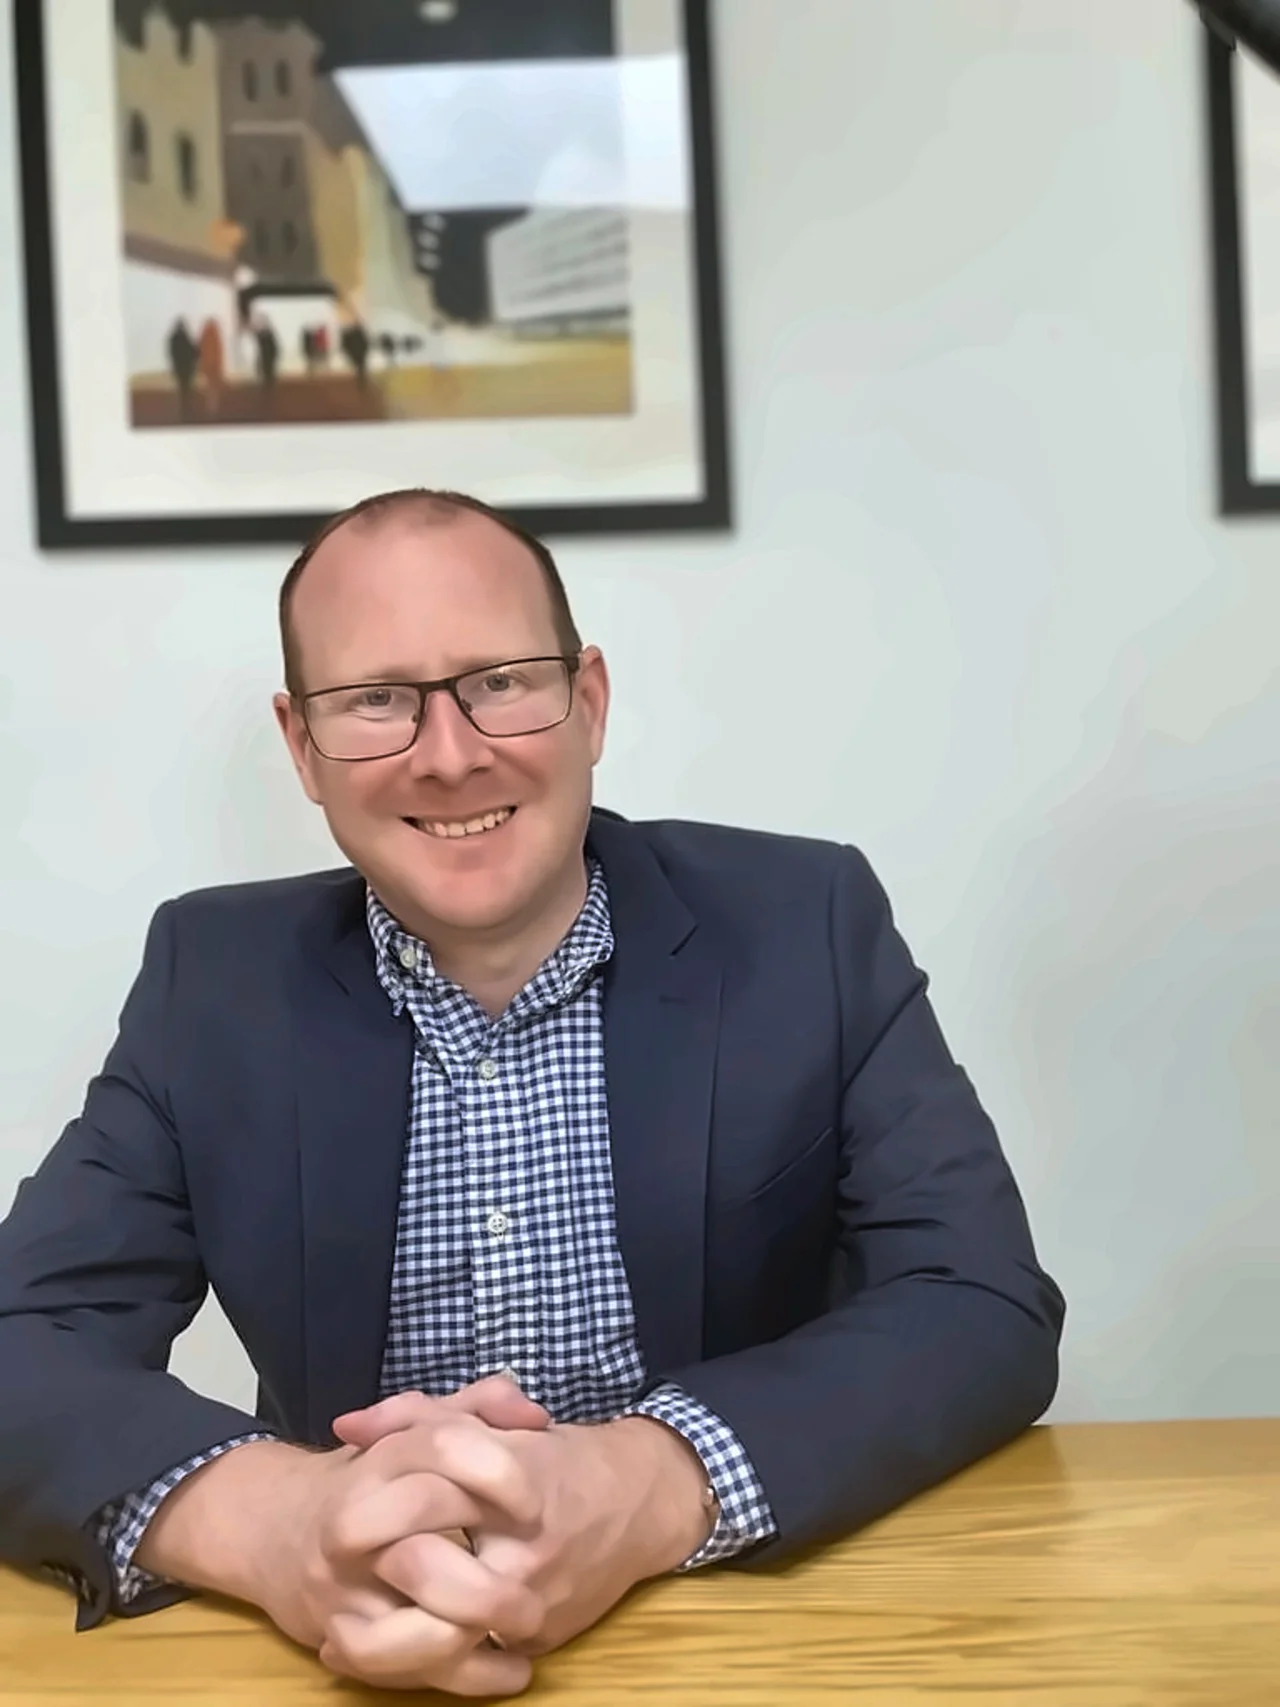
Meet James Hayes
I’ve been a financial adviser for 15+ years, working with locals across the Sutherland Shire, Inner West, and Sydney. Before that, I studied economics at the University of Sydney and completed my Diploma in Financial Planning at Kaplan.
Today, I run my own advice practice here in Caringbah. I’m not aligned with banks, product providers, or institutions, which means my advice is 100% about what’s best for you.
Outside of work, you’ll usually find me walking my dog or catching up with friends over coffee. Clients often tell me that working together feels less like dealing with a financial planner and more like chatting with a friendly neighbour who happens to know a lot about super and tax. And that’s exactly how I like it.
You’ve Worked for Your Money. Now, Make Your Money Work for You.
Most of my clients tell me the biggest change isn’t the plan itself but the relief of finally having someone they trust to handle it with them. If you’d like that weight off your shoulders, let’s chat. The sooner you start, the better your options.
Good To Know
FAQs
A financial planner helps with super & SMSFs, TTR, retirement, investments (shares & ETFs, first home, property, ethical), inheritance, insurance, pension, aged care, and wills & estate planning. They identify your goals, analyse your situation, prepare a written plan, explain risks, and recommend strategies. Legally, they must act in your best interests, keep advice documented, and update it as laws or circumstances change.
Being licensed by ASIC (opens in a new tab) means your financial adviser meets strict professional and ethical standards set by Australia’s financial regulator. It gives you protection as a client because they have a legal duty to act in your best interests (opens in a new tab) and are required to keep their knowledge up to date.
In Australia, financial adviser is now the regulated term under ASIC, but financial planner is often used interchangeably. Both must meet the same education, licensing, and ethics standards. The important thing is to verify that no matter what they call themselves, they are listed on ASIC’s Financial Adviser Register (opens in a new tab).
Check ASIC’s Financial Adviser Register (opens in a new tab), ask how they’re paid, and meet at least two advisers before choosing. Look for someone who explains things clearly, not with jargon. Experience with people in your stage of life matters more than fancy job titles or glossy brochures.
Trust comes from regulation and reputation. In Australia, advisers must be licensed by ASIC, follow fiduciary duties, and meet ongoing training standards. Ask for their ASIC rep number, read their Financial Services Guide, and check how they’re paid. Independence and transparency are key trust signals.
The main drawbacks are cost, potential conflicts of interest (if advisers are tied to products), and needing to share personal financial details. Check ASIC’s register (opens in a new tab) and choose an independent, long-term adviser to get trustworthy advice that is unbiased by corporate agendas.
James Hayes charges an upfront fee for advice and an ongoing fee, similar to a retainer, for continued support. The only commissions he may receive are insurance brokerage. All fees and commissions are disclosed upfront, and full transparency is required under ASIC’s financial advice regulations.
The initial phone call and first one-hour meeting are always complimentary. If you proceed with advice, the upfront fee ranges from $2,200 to $6,600 depending on the complexity of your situation. Ongoing advice is charged separately. If James can’t help, he’ll be upfront about it and point you in the right direction.
Yes, if you have super, investments, or retirement decisions to make. ASIC (opens in a new tab) and Deloitte (opens in a new tab) emphasise that quality advice can improve retirement outcomes and forestall costly mistakes. A good financial adviser educates you, never leaves you in the dark, or burdens you with technicalities.
Yes, in many cases. The portion of advice fees relating to producing assessable income (like super or investment strategies) is deductible. Fees related to estate planning or insurance usually aren’t. Advisers and accountants often work together to ensure that deductibility is correctly applied.
Yes, through government services like ASIC’s MoneySmart (opens in a new tab) and some super funds, which provide limited guidance. But it’s usually general, not personal. Independent financial advisers like James Hayes charge for personalised strategies because they are legally responsible for acting in your best interests and standing behind their recommendations.
There’s no strict minimum. Many advisers work with clients earning strong incomes or holding $150k–$200k+ in investable assets, including superannuation. Complexity is a bigger factor than net worth because when super, property, inheritance, or retirement decisions start involving risk, professional advice usually saves more money than it costs.
The earlier the better, because of the power of compounding. Major life events like starting work, buying property, marriage, inheritance, or retirement planning usually incite people to start.
DIY is possible if you’re confident with tax, super law, and investments. But Australia’s rules are complex, and mistakes are expensive. Advisers bring expertise, scenario modelling, and accountability. Many clients can technically DIY, but they choose advice to save time, stress, and costly missteps.
No. Advisers cannot log into accounts, move funds, or access your money directly. You authorise all changes through your super fund, bank, or provider. If an adviser also manages investments under a formal agreement, it must be disclosed in writing. ASIC licensing and compliance rules protect client funds.
Yes, because incomplete information leads to poor advice. Advisers base their recommendations on your income, debts, assets, and goals. If you hide details, the plan won’t fit reality. Advisers are bound by confidentiality, so honesty ensures the advice is safe, compliant, and genuinely in your interest.